the following information applies to the questions displayed below.\ntory enterprises pays $248,400 for…
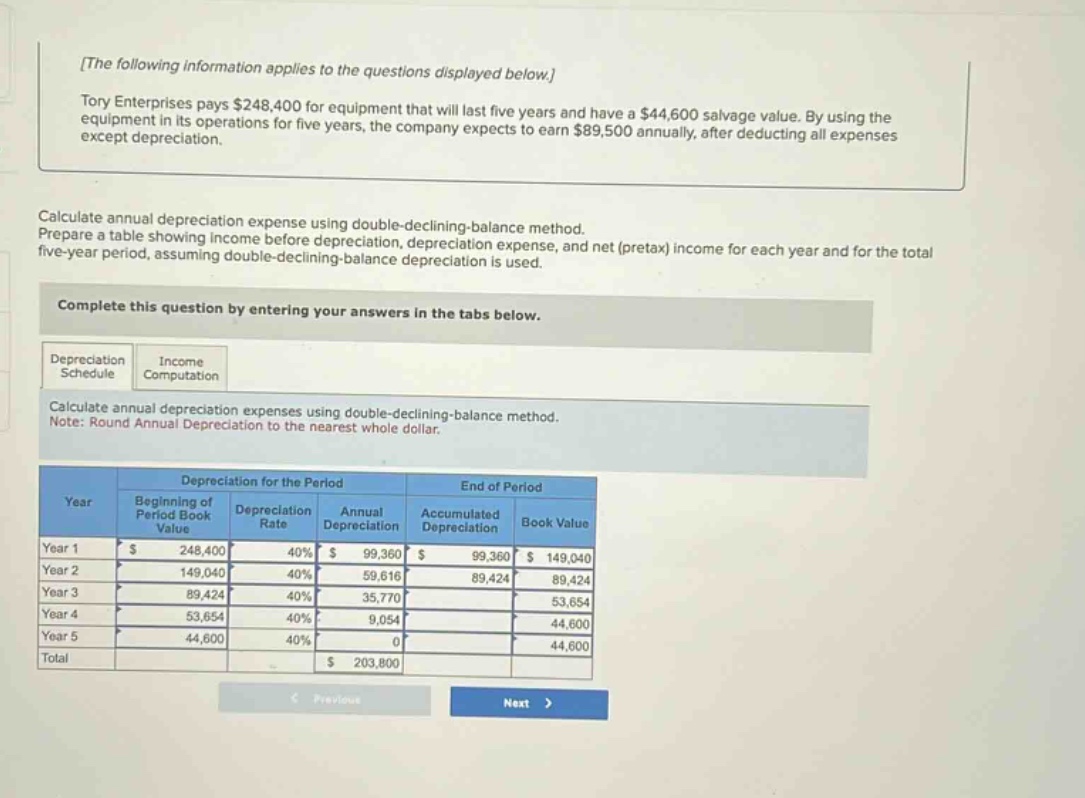
the following information applies to the questions displayed below.\ntory enterprises pays $248,400 for equipment that will last five years and have a $44,600 salvage value. by using the equipment in its operations for five years, the company expects to earn $89,500 annually, after deducting all expenses except depreciation.\ncalculate annual depreciation expense using double - declining - balance method.\nprepare a table showing income before depreciation, depreciation expense, and net (pretax) income for each year and for the total five - year period, assuming double - declining - balance depreciation is used.\ncomplete this question by entering your answers in the tabs below.\ndepreciation schedule income computation\ncalculate annual depreciation expenses using double - declining - balance method.\nnote: round annual depreciation to the nearest whole dollar.\ndepreciation for the period end of period\nyear beginning of period book value depreciation rate annual depreciation accumulated depreciation book value\nyear 1 $ 248,400 40% $ 99,360 $ 99,360 $ 149,040\nyear 2 149,040 40% 59,616 89,424 89,424\nyear 3 89,424 40% 35,770 53,654\nyear 4 53,654 40% 9,054 44,600\nyear 5 44,600 40% 0 44,600\ntotal $ 203,800
Answer
Explanation:
Step1: Calculate straight - line depreciation rate
The equipment has a useful life of 5 years. The straight - line depreciation rate $r_{sl}=\frac{1}{5}= 0.2$ or 20%. The double - declining - balance depreciation rate $r = 2\times r_{sl}=2\times0.2 = 0.4$ or 40%.
Step2: Calculate Year 1 depreciation
The beginning book value in Year 1 is $BV_0=$248,400$. The depreciation expense in Year 1, $Dep_1=r\times BV_0=0.4\times248400=$99,360$. The ending book value in Year 1, $BV_1 = BV_0 - Dep_1=248400 - 99360=$149,040$.
Step3: Calculate Year 2 depreciation
The beginning book value in Year 2 is $BV_1 = $149,040$. The depreciation expense in Year 2, $Dep_2=r\times BV_1=0.4\times149040=$59,616$. The ending book value in Year 2, $BV_2=BV_1 - Dep_2=149040 - 59616=$89,424$.
Step4: Calculate Year 3 depreciation
The beginning book value in Year 3 is $BV_2=$89,424$. The depreciation expense in Year 3, $Dep_3=r\times BV_2=0.4\times89424=$35,770$ (rounded to the nearest whole dollar). The ending book value in Year 3, $BV_3=BV_2 - Dep_3=89424 - 35770=$53,654$.
Step5: Calculate Year 4 depreciation
The beginning book value in Year 4 is $BV_3=$53,654$. The depreciation expense in Year 4, $Dep_4=r\times BV_3=0.4\times53654=$21,462$ (but we want to stop when we reach the salvage value). So we calculate the amount to bring the book value down to the salvage value. $Dep_4 = 53654 - 44600=$9,054$. The ending book value in Year 4 is the salvage value of $$44,600$. In Year 5, the depreciation is $0$ since the book value is already at the salvage value.
The total depreciation over the 5 - year period is $248400 - 44600=$203,800$.
Answer:
| Year | Beginning of Period Book Value | Depreciation Rate | Annual Depreciation | Accumulated Depreciation | End of Period Book Value |
|---|---|---|---|---|---|
| Year 1 | $$248,400$ | 40% | $$99,360$ | $$99,360$ | $$149,040$ |
| Year 2 | $$149,040$ | 40% | $$59,616$ | $$158,976$ | $$89,424$ |
| Year 3 | $$89,424$ | 40% | $$35,770$ | $$194,746$ | $$53,654$ |
| Year 4 | $$53,654$ | 40% | $$9,054$ | $$203,800$ | $$44,600$ |
| Year 5 | $$44,600$ | 40% | $$0$ | $$203,800$ | $$44,600$ |
| Total | $$203,800$ |