1. journalize the adjusting entry needed at december 31, 2023, for each situation. consider each fact…
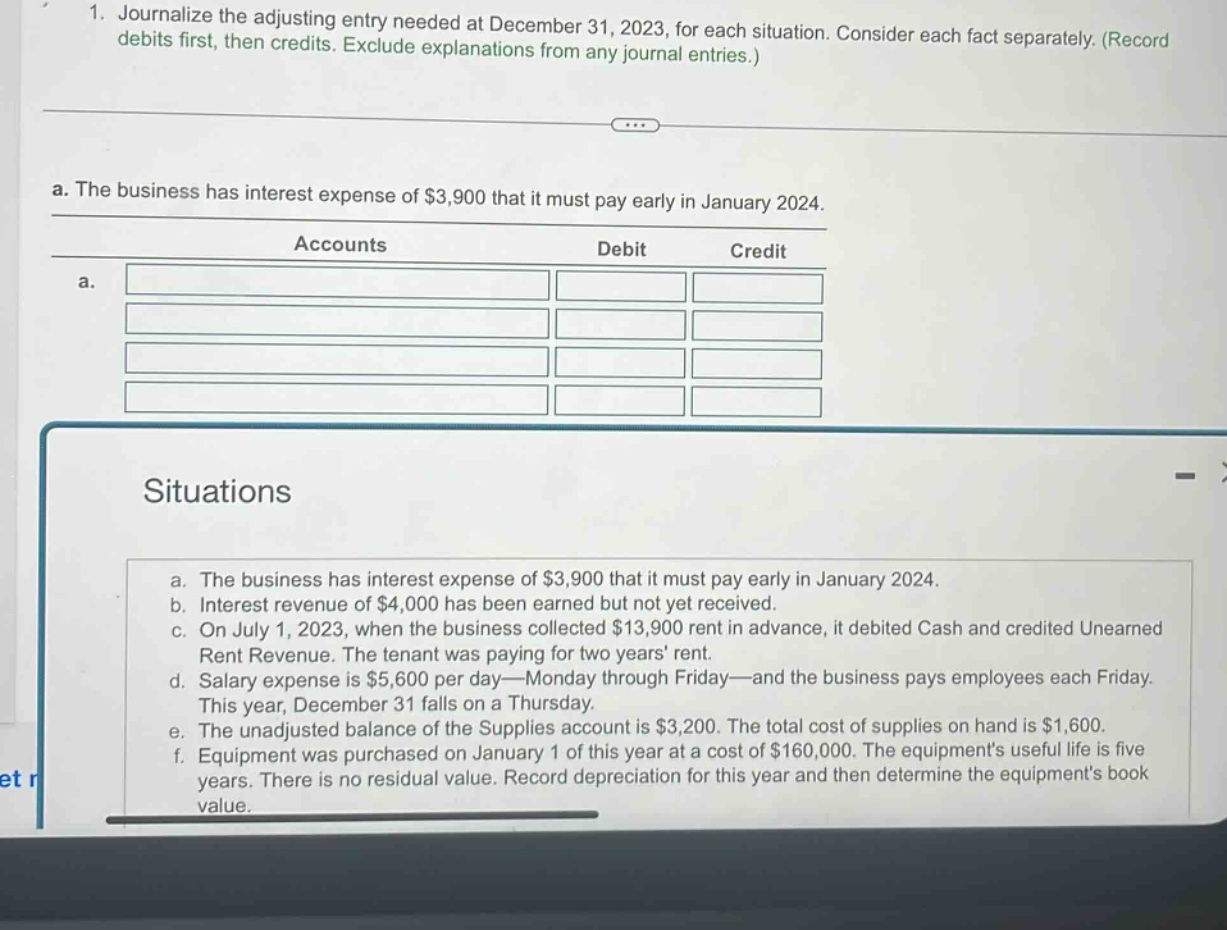
1. journalize the adjusting entry needed at december 31, 2023, for each situation. consider each fact separately. (record debits first, then credits. exclude explanations from any journal entries.) a. the business has interest expense of $3,900 that it must pay early in january 2024. accounts debit credit a. situations a. the business has interest expense of $3,900 that it must pay early in january 2024. b. interest revenue of $4,000 has been earned but not yet received. c. on july 1, 2023, when the business collected $13,900 rent in advance, it debited cash and credited unearned rent revenue. the tenant was paying for two years rent. d. salary expense is $5,600 per day—monday through friday—and the business pays employees each friday. this year, december 31 falls on a thursday. e. the unadjusted balance of the supplies account is $3,200. the total cost of supplies on hand is $1,600. f. equipment was purchased on january 1 of this year at a cost of $160,000. the equipments useful life is five years. there is no residual value. record depreciation for this year and then determine the equipments book value.
Answer
Explanation:
Step1: Identify the adjusting - entry concept
For accrued interest expense, we need to record the expense in the period it is incurred.
Step2: Determine the debit and credit accounts
Debit the Interest Expense account to recognize the expense, and credit the Interest Payable account as it is a liability to be paid in the future.
Answer:
| Accounts | Debit | Credit |
|---|---|---|
| Interest Expense | $3,900 | |
| Interest Payable | $3,900 |