june 30 sold a computer that was purchased on january 1, 2025. the computer cost $35,400 and had a useful…
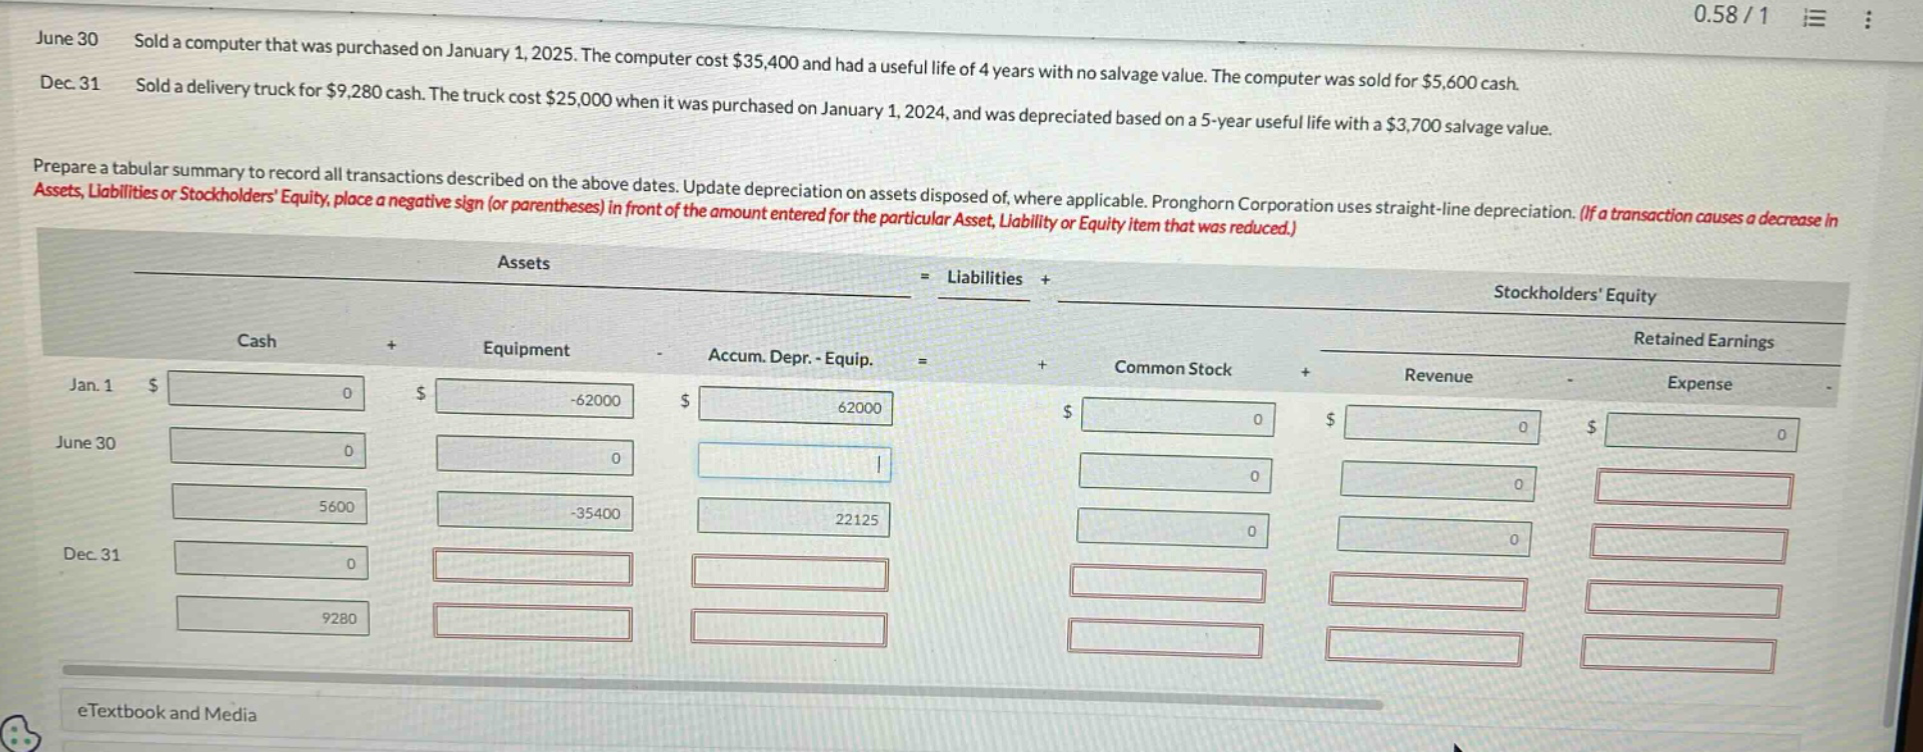
june 30 sold a computer that was purchased on january 1, 2025. the computer cost $35,400 and had a useful life of 4 years with no salvage value. the computer was sold for $5,600 cash. dec. 31 sold a delivery truck for $9,280 cash. the truck cost $25,000 when it was purchased on january 1, 2024, and was depreciated based on a 5 - year useful life with a $3,700 salvage value. prepare a tabular summary to record all transactions described on the above dates. update depreciation on assets disposed of, where applicable. pronghorn corporation uses straight - line depreciation. (if a transaction causes a decrease in assets, liabilities or stockholders equity, place a negative sign (or parentheses) in front of the amount entered for the particular asset, liability or equity item that was reduced.) assets = liabilities + stockholders equity cash + equipment - accum. depr. - equip. = + common stock + revenue - expense - retained earnings jan. 1 $ 0 $ -62000 $ 62000 $ 0 $ 0 $ 0 june 30 0 0 0 0 0 0 5600 -35400 22125 0 0 0 dec. 31 0 0 0 0 0 0 9280 0 0 0 0 0 etextbook and media
Answer
Explanation:
Step1: Calculate computer depreciation
The computer cost $35,400 with no - salvage value and a 4 - year useful life. The annual depreciation using straight - line method is $\frac{35400}{4}=8850$. From January 1, 2025 to June 30, 2025 (6 months or 0.5 years), the depreciation is $8850\times0.5 = 4425$.
Step2: Update computer's accumulated depreciation
Before disposal, the accumulated depreciation of the computer is $4425$.
Step3: Calculate gain or loss on computer disposal
The book value of the computer at disposal is $35400 - 4425=30975$. It is sold for $5600$, so the loss is $30975 - 5600 = 25375$.
Step4: Calculate truck depreciation
The truck cost $25,000 with a $3,700 salvage value and a 5 - year useful life. The annual depreciation is $\frac{25000 - 3700}{5}=\frac{21300}{5}=4260$. From January 1, 2024 to December 31, 2024 (1 year) and January 1, 2025 to December 31, 2025 (1 year), the total depreciation is $4260\times2 = 8520$.
Step5: Update truck's accumulated depreciation
Before disposal, the accumulated depreciation of the truck is $8520$.
Step6: Calculate gain or loss on truck disposal
The book value of the truck at disposal is $25000 - 8520 = 16480$. It is sold for $9280$, so the loss is $16480 - 9280=7200$.
| Date | Cash | Equipment | Accum. Depr. - Equip. | Common Stock | Revenue | Expense | Retained Earnings |
|---|---|---|---|---|---|---|---|
| Jan. 1 | 0 | - 62000 (This value seems not related to given transactions, assume it's a previous balance) | 62000 (This value seems not related to given transactions, assume it's a previous balance) | 0 | 0 | 0 | 0 |
| June 30 | 5600 | - 35400 | 4425 | 0 | 0 | 25375 | - 25375 |
| Dec. 31 | 9280 | - 25000 | 8520 | 0 | 0 | 7200 | - 7200 |
Answer:
| Date | Cash | Equipment | Accum. Depr. - Equip. | Common Stock | Revenue | Expense | Retained Earnings |
|---|---|---|---|---|---|---|---|
| Jan. 1 | 0 | - 62000 | 62000 | 0 | 0 | 0 | 0 |
| June 30 | 5600 | - 35400 | 4425 | 0 | 0 | 25375 | - 25375 |
| Dec. 31 | 9280 | - 25000 | 8520 | 0 | 0 | 7200 | - 7200 |