learning activity 3. cmr, bep, sensitivity analysis\nyvonne company’s income statement is shown below.\n\n|…
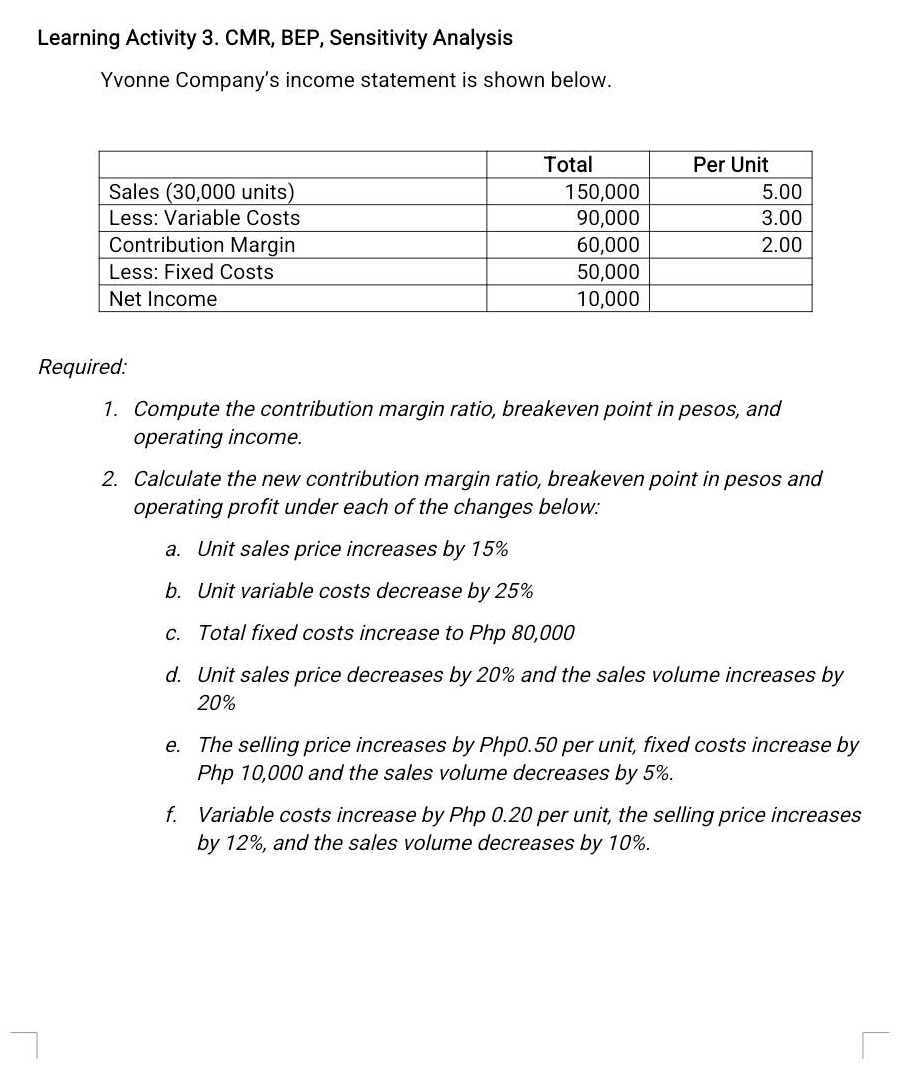
learning activity 3. cmr, bep, sensitivity analysis\nyvonne company’s income statement is shown below.\n\n| | total | per unit |\n|--|--|--| \n| sales (30,000 units) | 150,000 | 5.00 |\n| less: variable costs | 90,000 | 3.00 |\n| contribution margin | 60,000 | 2.00 |\n| less: fixed costs | 50,000 | |\n| net income | 10,000 | |\n\nrequired:\n1. compute the contribution margin ratio, breakeven point in pesos, and operating income.\n2. calculate the new contribution margin ratio, breakeven point in pesos and operating profit under each of the changes below:\n a. unit sales price increases by 15%\n b. unit variable costs decrease by 25%\n c. total fixed costs increase to php 80,000\n d. unit sales price decreases by 20% and the sales volume increases by 20%\n e. the selling price increases by php0.50 per unit, fixed costs increase by php 10,000 and the sales volume decreases by 5%.\n f. variable costs increase by php 0.20 per unit, the selling price increases by 12%, and the sales volume decreases by 10%.
Answer
Explanation:
Step1: Calculate original contribution - margin ratio
Contribution - margin ratio ($CMR$) is calculated as $\frac{Contribution\ Margin}{Sales}$. Given contribution margin = 60,000 and sales = 150,000. $CMR=\frac{60000}{150000}=0.4$
Step2: Calculate original break - even point in pesos
Break - even point in pesos ($BEP$) is calculated as $\frac{Fixed\ Costs}{CMR}$. Given fixed costs = 50,000 and $CMR = 0.4$. $BEP=\frac{50000}{0.4}=125000$
Step3: Calculate original operating income
Given as 10,000.
Part 2:
a. Unit sales price increases by 15%
Step1: Calculate new unit sales price
Original unit sales price = 5. New unit sales price = $5\times(1 + 0.15)=5.75$
Step2: Calculate new sales and contribution margin
New sales for 30,000 units = $5.75\times30000 = 172500$. Variable cost per unit = 3, total variable cost = $3\times30000=90000$. New contribution margin = $172500 - 90000=82500$
Step3: Calculate new contribution - margin ratio
$CMR=\frac{82500}{172500}\approx0.478$
Step4: Calculate new break - even point in pesos
$BEP=\frac{50000}{0.478}\approx104602.51$
Step5: Calculate new operating income
New operating income = $82500 - 50000 = 32500$
b. Unit variable costs decrease by 25%
Step1: Calculate new unit variable cost
Original unit variable cost = 3. New unit variable cost = $3\times(1 - 0.25)=2.25$
Step2: Calculate new contribution margin
New contribution margin per unit = $5-2.25 = 2.75$. For 30,000 units, total contribution margin = $2.75\times30000=82500$
Step3: Calculate new contribution - margin ratio
$CMR=\frac{82500}{150000}=0.55$
Step4: Calculate new break - even point in pesos
$BEP=\frac{50000}{0.55}\approx90909.09$
Step5: Calculate new operating income
New operating income = $82500 - 50000=32500$
c. Total fixed costs increase to Php 80,000
Step1: Contribution - margin ratio remains the same
$CMR = 0.4$ (from original calculation)
Step2: Calculate new break - even point in pesos
$BEP=\frac{80000}{0.4}=200000$
Step3: Calculate new operating income
Contribution margin = 60,000. New operating income = $60000 - 80000=-20000$
d. Unit sales price decreases by 20% and the sales volume increases by 20%
Step1: Calculate new unit sales price
Original unit sales price = 5. New unit sales price = $5\times(1 - 0.2)=4$
Step2: Calculate new sales volume
Original sales volume = 30,000. New sales volume = $30000\times(1 + 0.2)=36000$
Step3: Calculate new sales and contribution margin
New sales = $4\times36000 = 144000$. Variable cost per unit = 3, total variable cost = $3\times36000 = 108000$. New contribution margin = $144000-108000 = 36000$
Step4: Calculate new contribution - margin ratio
$CMR=\frac{36000}{144000}=0.25$
Step5: Calculate new break - even point in pesos
$BEP=\frac{50000}{0.25}=200000$
Step6: Calculate new operating income
New operating income = $36000 - 50000=-14000$
e. The selling price increases by Php0.50 per unit, fixed costs increase by Php 10,000 and the sales volume decreases by 5%
Step1: Calculate new unit sales price
Original unit sales price = 5. New unit sales price = $5 + 0.5=5.5$
Step2: Calculate new sales volume
Original sales volume = 30,000. New sales volume = $30000\times(1 - 0.05)=28500$
Step3: Calculate new sales and contribution margin
New sales = $5.5\times28500=156750$. Variable cost per unit = 3, total variable cost = $3\times28500 = 85500$. New contribution margin = $156750-85500 = 71250$
Step4: Calculate new contribution - margin ratio
$CMR=\frac{71250}{156750}\approx0.455$
Step5: Calculate new break - even point in pesos
New fixed costs = $50000 + 10000=60000$. $BEP=\frac{60000}{0.455}\approx131868.13$
Step6: Calculate new operating income
New operating income = $71250 - 60000 = 11250$
f. Variable costs increase by Php 0.20 per unit, the selling price increases by 12%, and the sales volume decreases by 10%
Step1: Calculate new unit sales price
Original unit sales price = 5. New unit sales price = $5\times(1 + 0.12)=5.6$
Step2: Calculate new unit variable cost
Original unit variable cost = 3. New unit variable cost = $3+0.2 = 3.2$
Step3: Calculate new sales volume
Original sales volume = 30,000. New sales volume = $30000\times(1 - 0.1)=27000$
Step4: Calculate new sales and contribution margin
New sales = $5.6\times27000=151200$. Total variable cost = $3.2\times27000 = 86400$. New contribution margin = $151200-86400 = 64800$
Step5: Calculate new contribution - margin ratio
$CMR=\frac{64800}{151200}=0.429$
Step6: Calculate new break - even point in pesos
$BEP=\frac{50000}{0.429}\approx116550.12$
Step7: Calculate new operating income
New operating income = $64800 - 50000 = 14800$
Answer:
- Contribution - margin ratio: 0.4; Break - even point in pesos: 125000; Operating income: 10000
a. Contribution - margin ratio: 0.478; Break - even point in pesos: 104602.51; Operating income: 32500 b. Contribution - margin ratio: 0.55; Break - even point in pesos: 90909.09; Operating income: 32500 c. Contribution - margin ratio: 0.4; Break - even point in pesos: 200000; Operating income: - 20000 d. Contribution - margin ratio: 0.25; Break - even point in pesos: 200000; Operating income: - 14000 e. Contribution - margin ratio: 0.455; Break - even point in pesos: 131868.13; Operating income: 11250 f. Contribution - margin ratio: 0.429; Break - even point in pesos: 116550.12; Operating income: 14800