portions of the financial statements for just in case technologies are provided below.\njust in case…
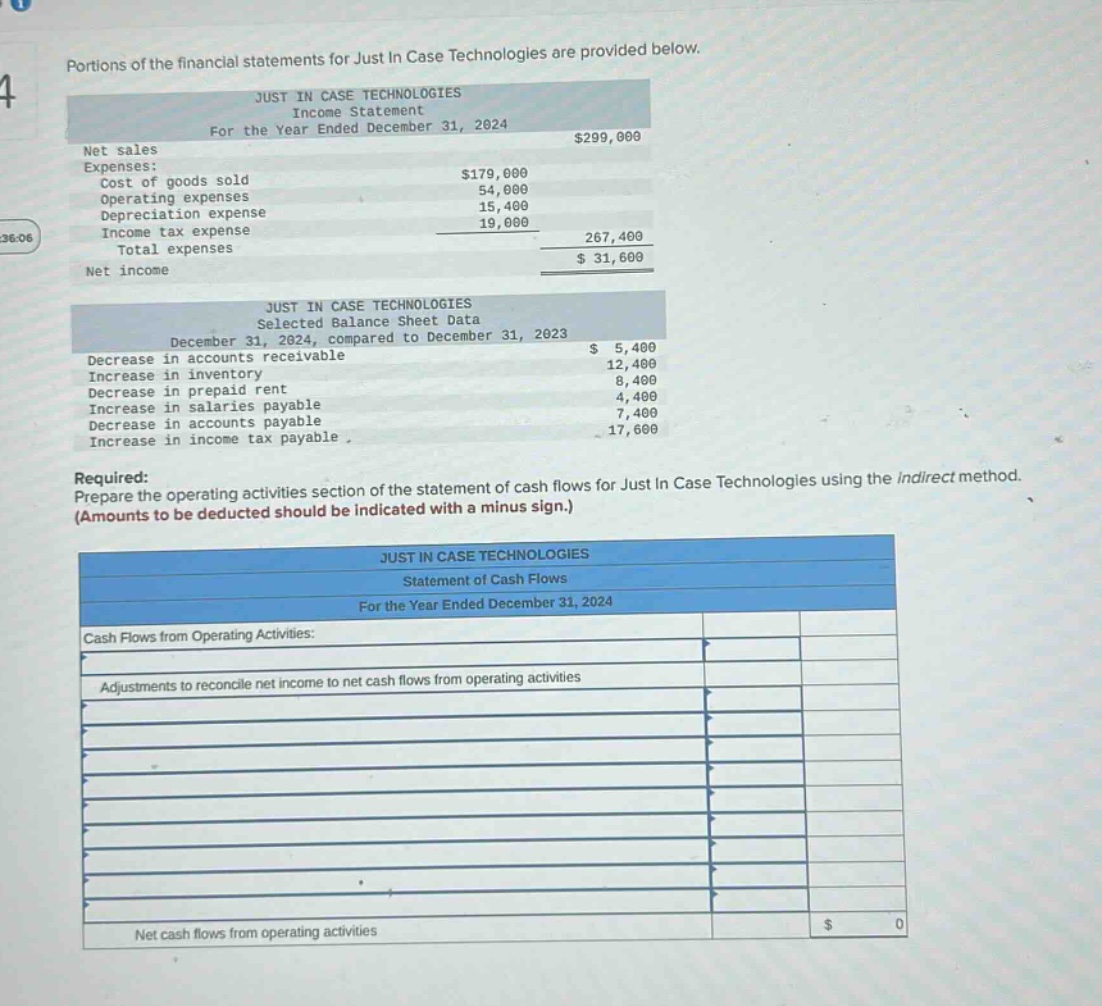
portions of the financial statements for just in case technologies are provided below.\njust in case technologies\nincome statement\nfor the year ended december 31, 2024\nnet sales $299,000\nexpenses:\ncost of goods sold $179,000\noperating expenses 54,000\ndepreciation expense 15,400\nincome tax expense 19,000\ntotal expenses 267,400\nnet income $31,600\njust in case technologies\nselected balance sheet data\ndecember 31, 2024, compared to december 31, 2023\ndecrease in accounts receivable $5,400\nincrease in inventory 12,400\ndecrease in prepaid rent 8,400\nincrease in salaries payable 4,400\ndecrease in accounts payable 7,400\nincrease in income tax payable 17,600\nrequired:\nprepare the operating activities section of the statement of cash flows for just in case technologies using the indirect method. (amounts to be deducted should be indicated with a minus sign.)\njust in case technologies\nstatement of cash flows\nfor the year ended december 31, 2024\ncash flows from operating activities:\nadjustments to reconcile net income to net cash flows from operating activities\nnet cash flows from operating activities $0
Answer
Explanation:
Step1: Start with net income
Net income is the starting - point for the indirect method. Given net income = $31,600.
Step2: Add decrease in accounts receivable
A decrease in accounts receivable means cash was collected. Add $5,400. New total = $31,600 + $5,400=$37,000.
Step3: Subtract increase in inventory
An increase in inventory means cash was used to purchase inventory. Subtract $12,400. New total = $37,000−$12,400 = $24,600.
Step4: Add decrease in prepaid rent
A decrease in prepaid rent means cash was not used for rent this period. Add $8,400. New total = $24,600 + $8,400=$33,000.
Step5: Add increase in salaries payable
An increase in salaries payable means less cash was paid for salaries. Add $4,400. New total = $33,000 + $4,400=$37,400.
Step6: Subtract decrease in accounts payable
A decrease in accounts payable means cash was used to pay off debts. Subtract $7,400. New total = $37,400−$7,400 = $30,000.
Step7: Add increase in income tax payable
An increase in income tax payable means less cash was paid for taxes. Add $17,600. New total = $30,000+ $17,600=$47,600.
Answer:
| Cash Flows from Operating Activities | Amount |
|---|---|
| Net income | $31,600 |
| Adjustments to reconcile net income to net cash flows from operating activities: | |
| Decrease in accounts receivable | $5,400 |
| Increase in inventory | -$12,400 |
| Decrease in prepaid rent | $8,400 |
| Increase in salaries payable | $4,400 |
| Decrease in accounts payable | -$7,400 |
| Increase in income tax payable | $17,600 |
| Net cash flows from operating activities | $47,600 |