question 19 (mandatory) (2 points) listen an overstatement of ending inventory will cause an overstatement…
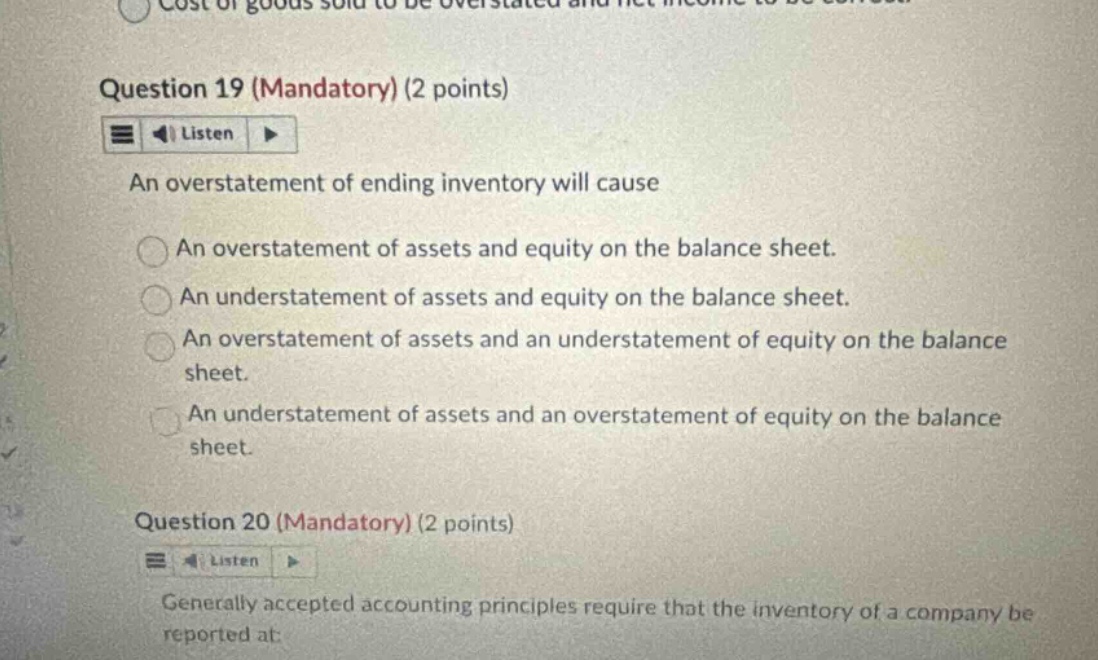
question 19 (mandatory) (2 points) listen an overstatement of ending inventory will cause an overstatement of assets and equity on the balance sheet. an understatement of assets and equity on the balance sheet. an overstatement of assets and an understatement of equity on the balance sheet. an understatement of assets and an overstatement of equity on the balance sheet. question 20 (mandatory) (2 points) listen generally accepted accounting principles require that the inventory of a company be reported at:
Answer
Brief Explanations:
- For Question 19: Ending inventory is an asset. An over - statement of ending inventory will increase the asset value on the balance sheet. Since Assets = Liabilities + Equity and liabilities are unchanged, equity will also be overstated.
- For Question 20: The question is incomplete, but generally, GAAP requires inventory to be reported at the lower of cost or net realizable value.
Answer:
Question 19: An overstatement of assets and equity on the balance sheet. Question 20: Incomplete question, no answer provided.