required information\n(the following information applies to the questions displayed below.)\nfollowing are…
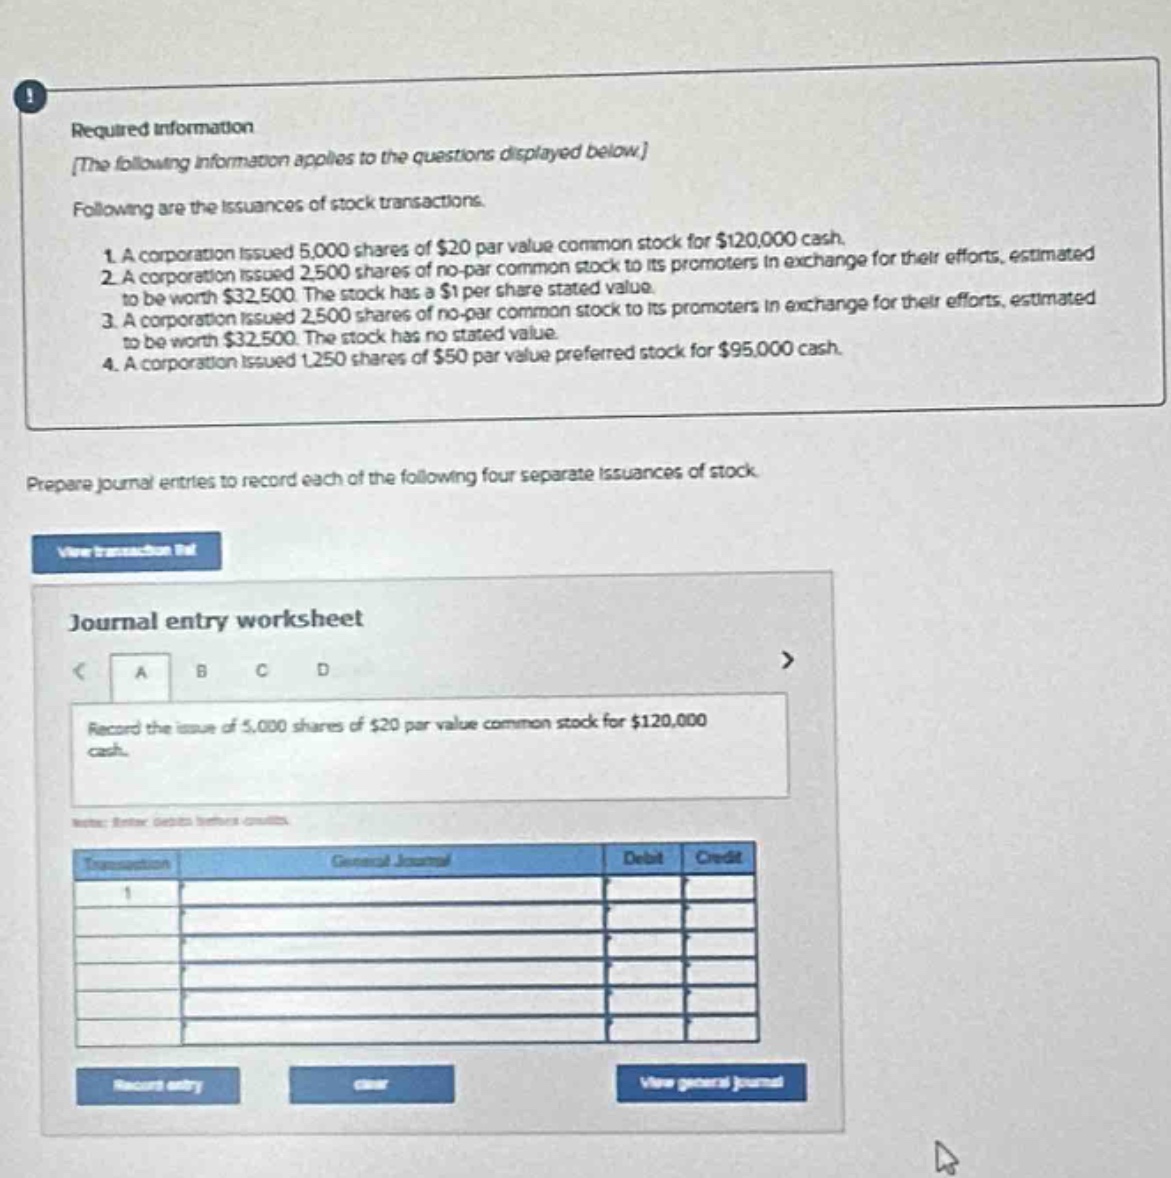
required information\n(the following information applies to the questions displayed below.)\nfollowing are the issuances of stock transactions.\n1. a corporation issued 5,000 shares of $20 par - value common stock for $120,000 cash.\n2. a corporation issued 2,500 shares of no - par common stock to its promoters in exchange for their efforts, estimated to be worth $32,500. the stock has a $1 per share stated value.\n3. a corporation issued 2,500 shares of no - par common stock to its promoters in exchange for their efforts, estimated to be worth $32,500. the stock has no stated value.\n4. a corporation issued 1,250 shares of $50 par - value preferred stock for $95,000 cash.\nprepare journal entries to record each of the following four separate issuances of stock.\njournal entry worksheet\nrecord the issue of 5,000 shares of $20 par - value common stock for $120,000 cash.
Answer
Explanation:
Step1: Transaction 1 - Calculate par - value amount
The par - value of common stock = Number of shares × Par value per share. For 5,000 shares of $20 par - value common stock, the par - value amount is $5000\times20=$100000$. The cash received is $120,000. The excess of cash over par value is $120000 - 100000=$20000$. The journal entry is:
| Transaction | General Journal | Debit | Credit |
|---|---|---|---|
| 1 | Cash | $120,000 | |
| Common Stock, $20 par value | $100,000 | ||
| Paid - in Capital in Excess of Par - Common Stock | $20,000 |
Step2: Transaction 2 - Calculate stated - value amount
The stated - value of common stock = Number of shares × Stated value per share. For 2,500 shares of $1 stated - value common stock, the stated - value amount is $2500\times1=$2500$. The value of promoters' efforts is $32,500. The excess of the value of promoters' efforts over the stated value is $32500 - 2500=$30000$. The journal entry is:
| Transaction | General Journal | Debit | Credit |
|---|---|---|---|
| 2 | Organization Expenses | $32,500 | |
| Common Stock, $1 stated value | $2,500 | ||
| Paid - in Capital in Excess of Stated Value - Common Stock | $30,000 |
Step3: Transaction 3 - No - par, no stated - value
Since the stock has no par and no stated value, the entire value of the promoters' efforts is credited to the common stock account. The journal entry is:
| Transaction | General Journal | Debit | Credit |
|---|---|---|---|
| 3 | Organization Expenses | $32,500 | |
| Common Stock | $32,500 |
Step4: Transaction 4 - Calculate par - value amount
The par - value of preferred stock = Number of shares × Par value per share. For 1,250 shares of $50 par - value preferred stock, the par - value amount is $1250\times50=$62500$. The cash received is $95,000. The excess of cash over par value is $95000 - 62500=$32500$. The journal entry is:
| Transaction | General Journal | Debit | Credit |
|---|---|---|---|
| 4 | Cash | $95,000 | |
| Preferred Stock, $50 par value | $62,500 | ||
| Paid - in Capital in Excess of Par - Preferred Stock | $32,500 |
Answer:
| Transaction | General Journal | Debit | Credit |
|---|---|---|---|
| 1 | Cash | $120,000 | |
| Common Stock, $20 par value | $100,000 | ||
| Paid - in Capital in Excess of Par - Common Stock | $20,000 | ||
| 2 | Organization Expenses | $32,500 | |
| Common Stock, $1 stated value | $2,500 | ||
| Paid - in Capital in Excess of Stated Value - Common Stock | $30,000 | ||
| 3 | Organization Expenses | $32,500 | |
| Common Stock | $32,500 | ||
| 4 | Cash | $95,000 | |
| Preferred Stock, $50 par value | $62,500 | ||
| Paid - in Capital in Excess of Par - Preferred Stock | $32,500 |