required information\nknowledge check 01\non january 1, year 1, davidson corporation issues 1,000 shares of…
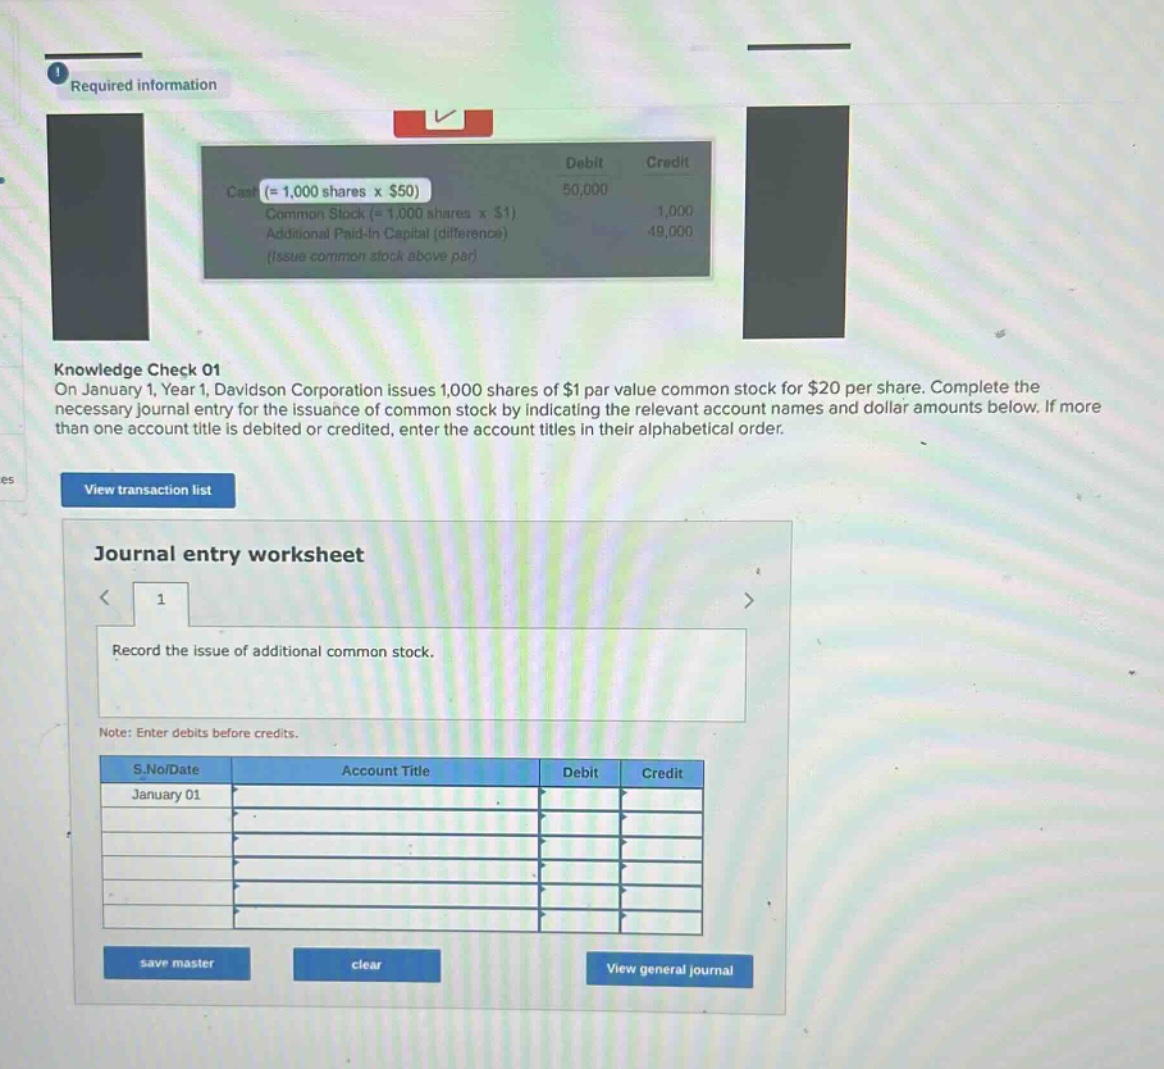
required information\nknowledge check 01\non january 1, year 1, davidson corporation issues 1,000 shares of $1 par - value common stock for $20 per share. complete the necessary journal entry for the issuance of common stock by indicating the relevant account names and dollar amounts below. if more than one account title is debited or credited, enter the account titles in their alphabetical order.\nview transaction list\njournal entry worksheet\n1\nrecord the issue of additional common stock.\nnote: enter debits before credits.\ns.no/date account title debit credit\njanuary 01
Answer
Answer:
| S.No/Date | Account Title | Debit | Credit |
|---|---|---|---|
| January 01 | Cash ($1,000\times$20) | 20,000 | |
| January 01 | Common Stock ($1,000\times$1) | 1,000 | |
| January 01 | Additional Paid - In Capital (difference) | 19,000 |
Explanation:
Step1: Calculate cash received
The company issues 1,000 shares at $20 per share. So, cash received is $1,000\times20 = 20,000$. Cash is debited as it is an increase in an asset account.
Step2: Calculate common - stock value
The par value of each share is $1 and 1,000 shares are issued. So, the value of common stock is $1,000\times1=1,000$. Common stock is credited as it is an equity account and its value is based on par - value.
Step3: Calculate additional paid - in capital
The difference between the amount received for the shares and the par - value of the shares is the additional paid - in capital. So, $20,000 - 1,000=19,000$. Additional paid - in capital is credited as it is part of equity.