the statement of retained earnings of gary larson publishers is presented below:\ngary larson…
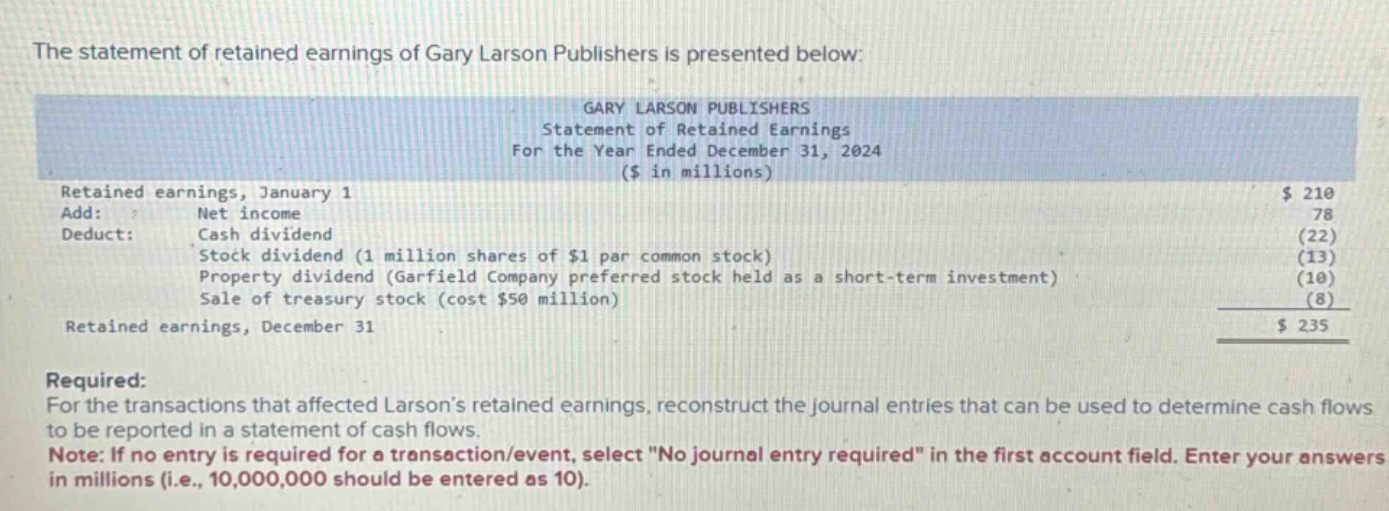
the statement of retained earnings of gary larson publishers is presented below:\ngary larson publishers\nstatement of retained earnings\nfor the year ended december 31, 2024\n($ in millions)\nretained earnings, january 1 $210\nadd: net income 78\ndeduct: cash dividend (22)\nstock dividend (1 million shares of $1 par common stock) (13)\nproperty dividend (garfield company preferred stock held as a short - term investment) (10)\nsale of treasury stock (cost $50 million) (8)\nretained earnings, december 31 $235\nrequired:\nfor the transactions that affected larsons retained earnings, reconstruct the journal entries that can be used to determine cash flows to be reported in a statement of cash flows.\nnote: if no entry is required for a transaction/event, select \no journal entry required\ in the first account field. enter your answers in millions (i.e., 10,000,000 should be entered as 10).
Answer
Explanation:
Step1: Record net - income addition
Net income increases retained earnings. The journal entry is to debit Income Summary (which is closed to Retained Earnings) and credit Retained Earnings. Debit: Income Summary 78 Credit: Retained Earnings 78
Step2: Record cash dividend
Cash dividends reduce retained earnings. The journal entry is to debit Retained Earnings and credit Cash. Debit: Retained Earnings 22 Credit: Cash 22
Step3: Record stock dividend
Stock dividends reduce retained earnings. For a $1 - par common stock dividend of 1 million shares, the journal entry is to debit Retained Earnings and credit Common Stock (at par value) and Additional - Paid - In Capital (if any, not given here just par value). Debit: Retained Earnings 13 Credit: Common Stock 13
Step4: Record property dividend
Property dividends reduce retained earnings. Debit Retained Earnings and credit the investment account (Garfield Company preferred stock). Debit: Retained Earnings 10 Credit: Investment in Garfield Company Preferred Stock 10
Step5: Sale of treasury stock
The sale of treasury stock does not affect retained earnings directly. So, No journal entry required for retained - earnings impact on this transaction for the purpose of this problem.
Answer:
| Transaction | Debit Account (in millions) | Credit Account (in millions) |
|---|---|---|
| Net income | Income Summary 78 | Retained Earnings 78 |
| Cash dividend | Retained Earnings 22 | Cash 22 |
| Stock dividend | Retained Earnings 13 | Common Stock 13 |
| Property dividend | Retained Earnings 10 | Investment in Garfield Company Preferred Stock 10 |
| Sale of treasury stock | No journal entry required | No journal entry required |